 28°C
Education Industry in the Dominican Republic: Market, Investment and Business Opportunities
The education industry in the Dominican Republic extends far beyond schools and universities. Private education providers, technical training centers, online learning platforms, educational technology companies and specialized service suppliers serve a large student population and an economy that needs new skills. Understanding the industry's structure, competitive pressures and sources of demand helps investors and businesses identify opportunities across the education value chain.


The education industry in the Dominican Republic is a diverse market that combines traditional educational institutions with vocational training, professional development, digital learning and a growing range of services for schools and universities. Its commercial activity is shaped by household spending, employer demand for qualified workers, technological adoption and the need to develop skills across the economy.
For businesses and investors, the market offers several distinct entry points. Private schools and universities operate directly with students and families, while technical training providers serve individuals seeking employment and companies investing in workforce development. Educational technology firms, software vendors, publishers, transport operators and facility service providers participate in the sector without necessarily delivering instruction themselves.
The industry’s scale is supported by a large education system. During the 2024–2025 school year, the Dominican Republic recorded 2,612,882 students across 10,648 educational centers at the pre-university level. Separately, higher education institutions enrolled 520,524 students in 2024, according to the Ministry of Higher Education, Science and Technology (MESCyT). These figures describe different segments and should not be added together without considering differences in coverage and possible overlap.
How the Education Industry Is Structured
The Dominican education market consists of several interconnected segments, each with its own customers, revenue models, investment requirements and competitive dynamics.
Private schools and early childhood education centers generate revenue primarily through tuition and related fees. Their services may include preschool education, primary and secondary schooling, language instruction, extracurricular activities, transportation and extended-day care.
Universities and higher education institutions offer undergraduate and postgraduate degrees, technical programs, professional certificates and continuing education. Private institutions compete through program availability, location, scheduling, facilities, reputation and the perceived relevance of their qualifications to employers.
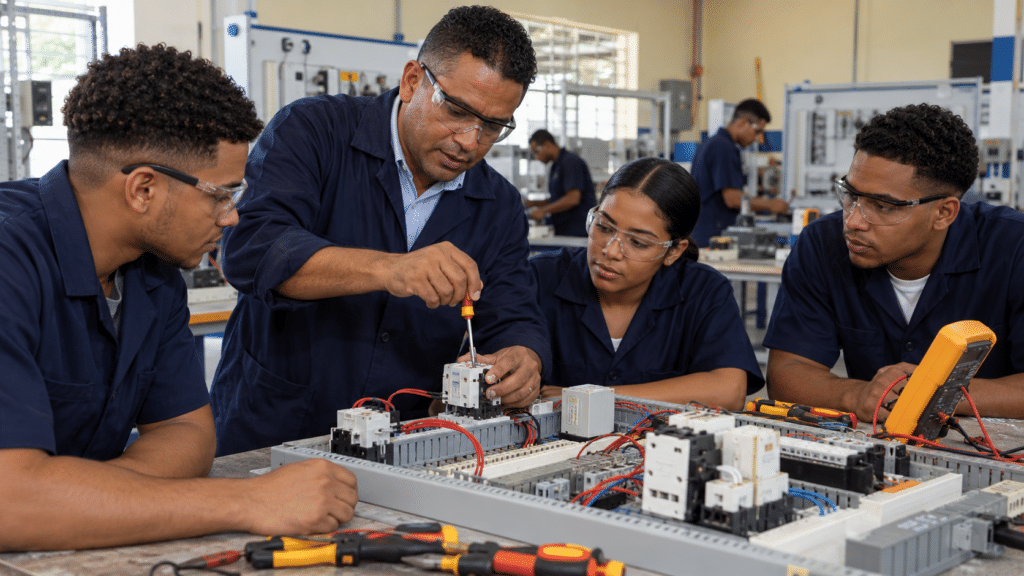
Technical and vocational training providers deliver practical skills for employment in areas such as hospitality, business administration, information technology, electricity, logistics, healthcare support and industrial operations. Their customers may be individuals, employers or organizations that finance training for specific workforce needs.
Online learning and educational technology companies provide digital courses, learning management systems, assessment tools, virtual classrooms, educational content and administrative software. Some operate directly in the consumer market, while others sell subscriptions or services to schools, universities and employers.
Auxiliary education services include educational publishing, school supplies, uniforms, furniture, laboratory equipment, internet connectivity, cybersecurity, building maintenance, transportation, food services and consulting. These suppliers can serve public and private institutions without competing for student enrollment.
These segments overlap. A private school may sell language courses, use an external digital learning platform and contract out transportation. A university may combine tuition revenue with corporate training, research partnerships and professional certification programs. For suppliers, this creates opportunities to serve multiple types of institutional customers through a single product or service.
Market Size and Demand for Education
The scale of the education industry is best understood through enrollment, institutional capacity and the range of services purchased by families and employers. A single national revenue figure would be misleading without a consistent definition of which activities count as part of the industry and comparable data on tuition, public spending, private expenditure and ancillary services.
Official figures nevertheless provide a useful picture of the market’s underlying demand. The 2024–2025 pre-university school year included 2.61 million students, while the higher education sector enrolled more than half a million students in 2024. Private institutions accounted for 581,593 pre-university students, or 22.3% of that enrollment. In higher education, private institutions enrolled 295,866 students, equivalent to 56.8% of the total.
The figures reveal different commercial conditions across the market. Private schools serve a substantial minority of school-age students, whereas private institutions account for a majority of higher education enrollment. The university market therefore has a particularly important role for private operators, although institutional scale and enrollment alone do not establish profitability.
Demand is influenced by several factors:
Household preferences and purchasing power. Families may pay for private schooling when they value a particular language offering, location, schedule, facilities or educational environment. The ability to sustain those payments depends on household income, tuition levels and competing expenses.
Employment and career progression. Students and working adults seek qualifications that can improve access to jobs, support promotion or enable a career change. Training linked to identifiable employment needs may be easier to position commercially than courses with unclear outcomes.
Business demand for skills. Employers need staff who can use digital systems, communicate with customers, manage operations and perform technical tasks. When existing qualifications do not fully meet these requirements, companies may purchase additional training or work with providers to develop tailored programs.
Geographic concentration. Santo Domingo and the wider capital area, along with Santiago and other urban centers, provide substantial pools of students, employers and institutional customers. Demand also exists in regional markets, where local industry, population distribution and the availability of established providers shape the opportunity.
Changing learning needs. English proficiency, digital skills, management training and short professional courses create demand beyond conventional school and university enrollment. These services can reach adults who are not pursuing a full academic qualification.
Private Schools and Early Childhood Education
Private schools are among the most visible commercial participants in the industry. Their operating models range from small neighborhood institutions to larger schools with extensive facilities, multiple grade levels, language programs and extracurricular activities.
During the 2024–2025 school year, 2,726 of the country’s 10,648 pre-university educational centers were privately managed, representing 25.6% of the total. These institutions enrolled 581,593 students, or 22.3% of pre-university enrollment. The figures show that the private sector is a meaningful part of the market, but they do not indicate how many institutions are profitable or how much revenue they generate.
Tuition is the principal revenue source for many private schools, supplemented where applicable by registration fees, meals, transportation, uniforms, extracurricular activities and other services. These additional offerings can improve convenience for families and diversify revenue, although they also create operational complexity and additional costs.
Opening or expanding a school requires more than demand for classroom places. Investors must assess property costs, building suitability, safety, staffing, teaching resources, utilities, maintenance and the requirements applicable to educational institutions. Enrollment also needs to be sufficient to cover fixed costs throughout the academic year.
Competition often centers on location, reputation, affordability, class size, language provision, facilities and the quality of family communication. A school with high occupancy can still face financial pressure if tuition is too low relative to staffing and facility expenses. Conversely, a premium-priced institution needs a clearly defined customer base willing and able to pay for its offer.
Early childhood education presents a related opportunity. Parents may seek structured early learning and dependable care that fits their working schedules. Providers must balance affordability with staffing requirements, appropriate facilities and the need to maintain trust with families. The commercial model depends heavily on local demand, capacity utilization and operating standards.
Universities and the Higher Education Market
Higher education is a major segment of the Dominican education industry, encompassing universities, specialized institutions and technical higher education providers. Its revenue models include tuition, enrollment and administrative fees, postgraduate programs, professional education and, in some cases, corporate partnerships and research activities.
MESCyT recorded 520,524 higher education students in 2024. Universities accounted for 496,163 students, or 95.3% of the total, while technical higher education institutes and specialized higher education institutes accounted for the remainder. Private institutions enrolled 295,866 students, compared with 224,658 in the public sector.
The public Universidad Autónoma de Santo Domingo (UASD) was the country’s largest higher education institution by enrollment, with 194,909 students. Private providers therefore compete in a market that includes a large public university as well as other public and private institutions.
For private universities, commercial performance depends on more than the number of students enrolled. Relevant factors include tuition revenue per student, program mix, retention, graduation rates, teaching costs, campus utilization, investment in laboratories and technology, and the ability to maintain a strong reputation.
Programs connected to business operations, healthcare, engineering, technology and other professional fields may attract students seeking specific career pathways. However, demand should be assessed by program rather than assumed across the sector. Popularity, graduate employment and willingness to pay can vary significantly between disciplines.
Postgraduate degrees, executive education, professional certificates and evening or weekend programs provide potential ways to serve working adults without relying exclusively on traditional undergraduate enrollment. Flexible scheduling can expand the addressable market, but program development must still account for qualified instructors, appropriate facilities, academic requirements and credible outcomes.
Investors considering higher education should also distinguish between acquiring or financing an operating business and establishing a new institution. Authorization, institutional evaluation, academic requirements and other applicable rules can affect the time, cost and feasibility of entering the market. A commercial opportunity does not automatically translate into permission to operate.
Technical and Vocational Training
Technical and vocational education serves a different market from conventional academic education. It focuses on practical competencies that can be applied in specific jobs, workplaces or self-employment activities. Programs may be short, modular or structured around a defined occupation, making them relevant to people who need to acquire skills without committing to a multi-year degree.
The National Institute for Technical and Vocational Training (INFOTEP) is an important participant in this segment. Its role and scale illustrate the importance of workforce training within the broader economy. INFOTEP reported training 684,813 participants in 2024, with courses covering areas including sales, commerce, information technology, accounting, hospitality, health-related services, administration, electricity and electronics.
That volume demonstrates substantial activity in technical training, but it should not be interpreted as the size of the private vocational training market. INFOTEP’s reported participation includes its own training activity and does not measure the revenue, enrollment or profitability of independent commercial providers.
Private operators can compete by focusing on specific occupations, serving employer requirements or offering scheduling and delivery models that meet the needs of working adults. Potential areas include software and digital tools, language training, bookkeeping, customer service, tourism operations, logistics, equipment maintenance and technical trades.
Employer-sponsored training is another business model. Instead of selling individual courses to students, a provider contracts with a company to train groups of employees. This can produce repeat business and reduce dependence on consumer marketing, particularly when the training addresses recurring operational needs.
Successful providers must demonstrate that their courses deliver practical value. Relevant indicators include course completion, skills assessment, employer satisfaction, repeat contracts and, where measurable, employment or promotion outcomes. Training providers should avoid promising guaranteed jobs or salary increases unless such claims can be substantiated.
Online Learning and Educational Technology
Online learning expands the education market beyond the capacity and location of physical classrooms. It can serve students enrolled in conventional institutions, professionals seeking new skills, employers training staff and individuals pursuing independent learning.
The commercial landscape includes several models: subscription-based course libraries, live online instruction, self-paced courses, tutoring platforms, language-learning products, learning management systems, digital assessment tools and software used to manage admissions, attendance, billing and student records.
Online education can reduce some of the costs associated with physical delivery, including classroom space and certain travel expenses. It does not eliminate the costs of course production, qualified instructors, platform development, customer acquisition, technical support, content updates or student retention.
For providers serving Dominican customers, pricing and usability matter. Courses need to reflect local purchasing power and the schedules of students who may also work or have family responsibilities. Reliable access through mobile devices, straightforward payment options, responsive support and content in the appropriate language can influence whether users complete a course and continue paying for a service.
Educational technology suppliers may find opportunities by selling to established schools and universities rather than building a consumer-facing education brand. Potential services include school administration software, digital learning platforms, cybersecurity, cloud infrastructure, online assessment, digital libraries and systems for communication with families.
Institutional customers may require demonstrations, integration with existing systems, staff training, data protection measures and ongoing technical support. The sales cycle can therefore be longer than a direct consumer transaction. Suppliers should assess the institution’s budget, procurement process, implementation capacity and willingness to renew before treating a contract as recurring revenue.
Digital delivery also introduces risks. Low-cost international platforms can compete directly with local providers, while free content limits what some learners are willing to pay for. A sustainable business usually needs a distinct advantage, such as local relevance, recognized credentials, personalized instruction, employer connections or a service that saves institutions measurable time and money.
Auxiliary Services and the Education Supply Chain
Not every education business needs to operate a school or teach a course. Educational institutions depend on a broad network of suppliers, and some of the more accessible commercial opportunities are found in these supporting activities.
Educational materials and equipment. Schools and universities purchase books, workbooks, stationery, classroom furniture, science equipment, computers and other teaching resources. Suppliers may sell directly to institutions, work through distributors or provide specialized products for laboratories and technical programs.
Software and IT services. Institutions need reliable networks, devices, software, technical support and data management. Providers can compete through implementation services, maintenance agreements, subscription products and training for teachers or administrative staff.
Transportation and food services. School transport and meal provision can be important parts of the service package offered by educational institutions. These businesses require careful attention to safety, staffing, logistics, cost control and any applicable operating requirements.
Facilities and maintenance. Cleaning, security, repairs, energy management, construction, classroom refurbishment and equipment maintenance create recurring needs for institutions operating physical campuses.
Professional and administrative services. Schools and universities may purchase accounting, payroll, legal advice, marketing, recruitment, accreditation support, staff development and strategic consulting. Providers with specialized knowledge of educational organizations may be able to differentiate themselves from general service firms.
These markets can offer opportunities for small and medium-sized enterprises, especially when services can be standardized and sold to multiple institutions. However, supplier profitability depends on contract size, payment terms, staffing, transport or delivery costs, and the concentration of revenue among a small number of clients.
Investment Requirements and Operating Economics
The capital needed to enter the education industry varies substantially by business model. A digital course provider may begin with a relatively limited physical footprint, while a school or university may require significant expenditure on property, construction, equipment, technology and regulatory preparation.
For a private school, the principal financial considerations include facility acquisition or rental, classroom capacity, teacher salaries, administration, maintenance, utilities, insurance where applicable and educational resources. Revenue is commonly tied to enrollment and tuition collection, so a school may experience cash-flow pressure when student numbers fall or payments arrive late.
Universities face similar enrollment and staffing considerations, but their financial structure may be more complex. Laboratories, specialized equipment, libraries, campus infrastructure and program-specific personnel can raise costs. Expanding into a new discipline may require substantial investment before enough students enroll to support it.
Vocational providers often have a different cost structure. General classroom training may require limited specialized equipment, whereas courses in electricity, industrial maintenance, healthcare-related skills or other practical fields may need workshops, tools, consumables and safety measures. Employer contracts can help stabilize demand, but relying on a single client can expose the business to contract cancellations or changes in workforce priorities.
Online learning businesses need to account for content creation, platform costs, instructor compensation, customer acquisition and ongoing learner support. Their economics depend on the relationship between the cost of attracting a customer and the revenue earned over the customer’s lifetime. High registration numbers do not necessarily indicate a viable business if students do not complete courses, renew subscriptions or purchase additional products.
Across the industry, investors should examine:
Enrollment and capacity utilization. How many places are available, how many are occupied, and how much additional demand can be served without major capital expenditure?
Revenue quality. How much income comes from recurring tuition, subscriptions or contracts, and how much depends on one-off payments or seasonal sales?
Retention and collection. Do students continue from one term to the next? Are tuition and service fees collected on time?
Staffing costs. Can the institution recruit and retain qualified educators, trainers and technical employees within its financial model?
Regulatory and quality requirements. What authorizations, evaluations, operating standards or data protection obligations apply to the specific service?
Measurable outcomes. Can the provider demonstrate educational quality, student satisfaction, skills development or value for institutional customers?
These measures help distinguish genuine growth from expansion that increases costs without producing sustainable returns.
Employment and the Education Workforce
The education industry creates direct employment for teachers, lecturers, trainers, administrators, counselors, librarians, technicians, IT specialists, maintenance staff and managers. It also supports indirect employment in transportation, food services, construction, publishing, software, equipment supply and professional services.
Labor requirements vary by segment. Schools depend on teachers and support staff who can work with children and families. Universities need faculty members and specialized personnel for academic programs, research and administration. Technical training providers require instructors who understand both the subject matter and its practical application.
Recruiting qualified personnel is an important operating consideration. Institutions may need to compete for experienced teachers, bilingual staff, technology specialists and professionals with industry experience. Training and staff development add costs but can also improve consistency, service quality and retention.
Digital learning changes the mix of skills required rather than removing the need for people. Online providers still need course designers, instructors, student support staff, platform specialists and personnel responsible for quality assurance. Hybrid models can require staff to work effectively in both classroom and digital environments.
For investors, workforce planning should be treated as part of the business model from the beginning. An institution’s ability to recruit and retain qualified personnel affects enrollment capacity, service quality, reputation and compliance with applicable requirements.
Competition Across the Education Market
Competition comes from local private institutions, public providers, international education companies, independent instructors and digital platforms. The relevant competitors depend on what a customer wants to purchase. A private school competes with nearby schools, while a professional training company may compete with universities, employer-led programs, online course providers and free educational resources.
Price is only one factor. Families may value location, trust, facilities, language options and consistent communication. University students may consider program availability, schedule, reputation and career relevance. Employers may prioritize practical competencies, reliable delivery, measurable results and the ability to train staff without excessive disruption to operations.
Smaller providers can compete by specializing rather than trying to match every service offered by larger institutions. A training company focused on a specific technical skill or industry may develop stronger relationships with employers than a general provider with a broad but undifferentiated catalog.
Established institutions can benefit from reputation, alumni networks, facilities and existing enrollment. These advantages may be difficult for new entrants to reproduce quickly. However, smaller organizations can sometimes respond faster to changes in customer needs or introduce more flexible delivery formats.
International online platforms add another layer of competition. They can offer extensive content and established technology, but may not provide the local support, in-person instruction, employer relationships or context required by some Dominican customers. Local providers need to identify where their proximity and understanding of the market create a real advantage.
Regulation and Institutional Requirements
Education is a regulated activity, and the requirements depend on the type of institution and service. The Ministry of Education (MINERD) is responsible for the pre-university education sector, while MESCyT oversees higher education within its legal and institutional framework. Technical and vocational training operates through its own institutional arrangements, including INFOTEP’s role in workforce development.
Businesses should determine the applicable requirements before investing in a facility, launching a program or advertising a qualification. A private school, a university, a vocational training center and an online course business may face different requirements. The fact that instruction is delivered digitally does not automatically mean that every course or credential is exempt from relevant rules.
Institutional authorization, academic recognition, facility suitability, personnel qualifications, student records, advertising claims and consumer protection can all be relevant, depending on the business. Providers that offer credentials should clearly explain what those credentials represent and whether they have formal recognition where such recognition is claimed or required.
Investors should obtain current guidance from the relevant authorities and qualified local advisers before committing capital. Requirements can change, and compliance should be assessed against the specific activity rather than inferred from the rules governing another type of educational provider.
Official enrollment data and institutional statistics are available through the MESCyT statistics publications, which provide a starting point for evaluating the higher education market.
Growth Opportunities for Businesses and Investors
The strongest opportunities are not necessarily found in opening another general-purpose school or university. They may arise where customers face a specific problem that existing providers do not solve adequately, or where an established institution needs a more efficient way to deliver its services.
Career-focused training. Short courses and employer-linked programs can serve workers who need practical skills in digital tools, languages, administration, technical occupations or industry-specific procedures. Providers should validate demand with employers and prospective learners before building a large course catalog.
Corporate learning and development. Companies may need onboarding, management training, software instruction, customer service development and technical upskilling. A provider that can tailor content, schedule sessions around operations and report outcomes may secure repeat contracts.
Educational software and institutional services. Schools and universities need systems that simplify enrollment, billing, communication, assessment and record management. Suppliers that solve a clear operational problem and offer dependable support may develop recurring revenue through subscriptions and service agreements.
Hybrid and flexible learning. Programs that combine online content with live instruction, practical sessions or in-person assessments can serve students who need flexibility but still benefit from direct support. Their success depends on course design, learner engagement and the suitability of the format for the subject.
Specialized education services. Language instruction, tutoring, test preparation, professional certification support and targeted learning services can serve defined customer groups. Competition and willingness to pay should be tested at the local level before expanding to additional locations.
Equipment and facility solutions. Providers of classroom technology, laboratory equipment, energy-efficient systems, maintenance and educational furniture can serve institutions that need to upgrade or expand facilities. Commercial success depends on procurement access, product quality, service capability and the ability to manage payment terms.
Regional and industry-specific training. Businesses located near major employment centers may be able to develop courses aligned with the needs of local employers. Hospitality, tourism, logistics, commerce and technical services are examples of areas in which employers may require specialized training, although demand must be verified in each location.
Investors should distinguish between broad social demand for education and effective commercial demand for a particular product. A large student population does not guarantee that customers will pay for a new service, and a skill shortage does not automatically mean that a training provider can deliver a profitable program. Customer research, pilot courses, employer partnerships and realistic financial projections can reduce these uncertainties.
Risks and Challenges for Education Businesses
The sector has several structural risks. Private institutions are exposed to household purchasing power, enrollment changes and competition over tuition. Providers serving employers may face contract concentration, changing training budgets or demand for skills that become outdated quickly. Technology businesses must keep products secure, usable and compatible with customers’ existing systems.
Quality is another central challenge. Poor teaching, weak course design, unreliable administration or unclear qualification claims can damage reputation and reduce retention. In education, the consequences of a weak service may become visible only over time, making transparent communication and credible outcome measurement particularly important.
Capital-intensive institutions also face the risk of building capacity before demand is established. Property and staffing expenses can persist even when classrooms are underused. Expanding too quickly, relying on optimistic enrollment forecasts or setting tuition without understanding the full cost base can undermine financial stability.
Digital providers face their own pressures, including customer acquisition costs, competition from free content, platform dependence and low completion rates. A product that attracts initial interest but does not help learners achieve their goals may struggle to retain subscribers or generate repeat purchases.
Finally, the regulatory environment must be treated as an operating requirement rather than a final administrative step. Delays in authorization, changes in applicable rules or failure to meet institutional obligations can affect launch schedules, costs and the ability to offer certain services.
Assessing the Outlook for the Dominican Education Industry
The Dominican Republic’s education industry combines a large pre-university student population, a substantial higher education market and extensive demand for vocational training. Its commercial ecosystem includes institutions that teach students directly and businesses that provide the technology, materials, infrastructure and services needed to operate educational programs.
Future growth will depend on more than enrollment. Private providers must demonstrate value to families, universities need to maintain relevant and financially sustainable programs, and vocational businesses must connect training to the needs of learners and employers. Digital providers and suppliers can find opportunities by helping institutions improve access, administration, delivery and measurable outcomes.
For investors, the most useful starting point is a clearly defined customer and a specific need. Understanding local competition, the willingness to pay, staffing requirements, regulatory obligations and the economics of delivering the service is more reliable than assuming that the size of the education system alone guarantees an attractive return. Businesses that combine credible educational value with disciplined operations can identify opportunities across one of the country’s most extensive and varied service sectors.